



USD/JPY: Upside limited in absence of renewed US bond bloodbath
For all the talk about a reacceleration in US inflation and deluge of debt issuance, key US bond yields have yet to break higher.
Share this:

There is no greater influence on the USD/JPY than yield differentials between the United States and Japan, meaning a trade involving the pair is essentially the same as taking a directional view on the path for US bond yields. As long as the Bank of Japan persists with yield curve control – anchoring 10-year Japanese government bond (JGB) yields within 100 basis points of 0% -- it’s likely to remain that way for the foreseeable futures.
You can see the close relationship between the USD/JPY, shown in orange in the chart below, against the yield spread the United States enjoys over the Japan for benchmark government bonds in black. It’s not a perfect relationship by any means, but influential nonetheless.
2 and ten-year US bond yields have yet to hit fresh highs
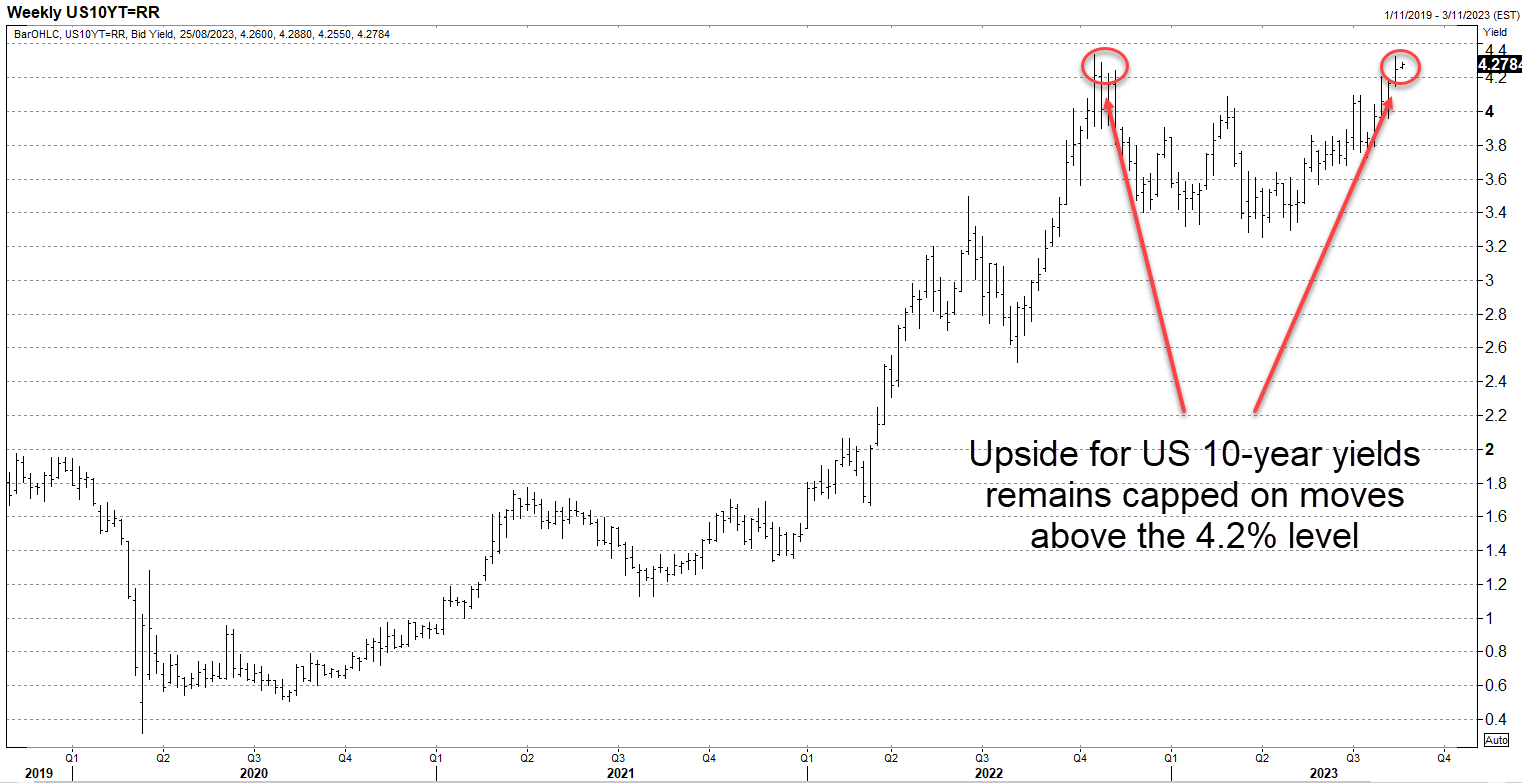
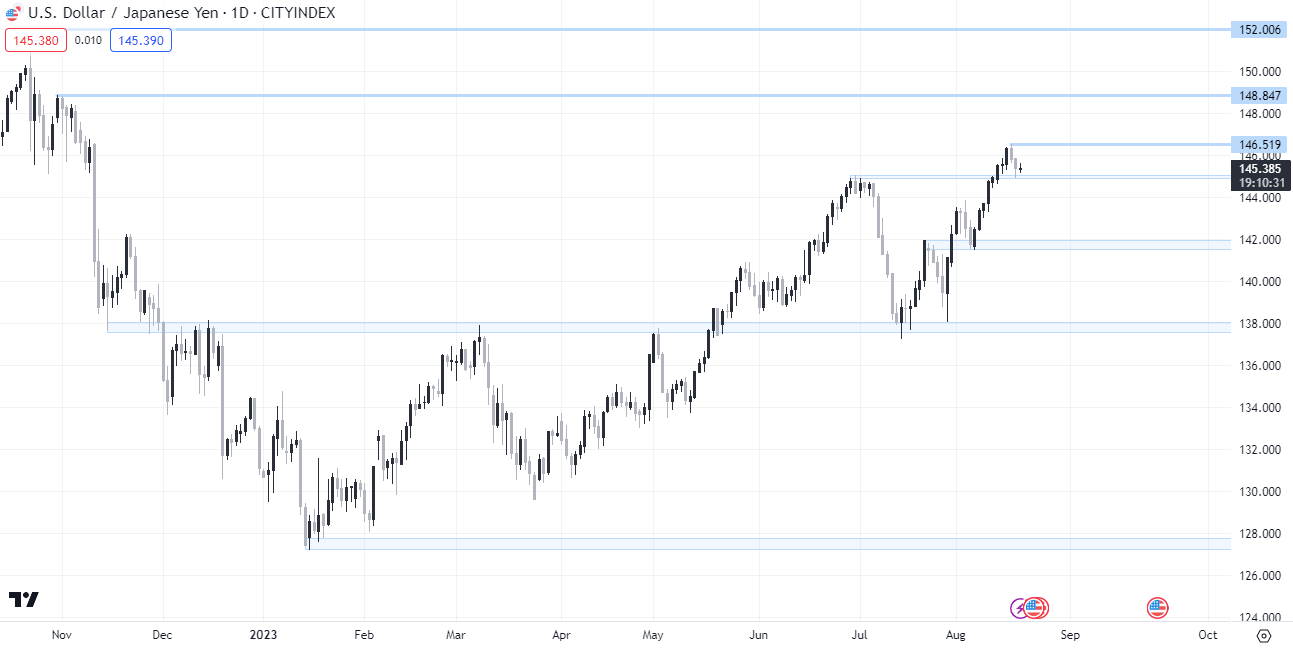
Having risen from around 0.5% during the peak of the coronavirus pandemic market panic to above 4.3% last week, helping to propel the USD/JPY from just above 101 to within touching distance of 147 last week, the question FX traders should be asking themselves is where are the directional risks for US Treasury yields now after such a dramatic move?
There’s clearly no shortage of bond bears out there right now, highlighting risks such as a reacceleration in US inflationary pressures, a deluge of new debt issuance, along with attempting to rollover vast amounts of existing debt into a far higher interest rate environment.
But even with these concerns, at time when the Federal Reserve is draining liquidity from the financial system by pursuing quantitative tightening, yields on US Treasuries are yet to break to fresh highs outside the extreme longer-end of the US curve. Two-year yields – highly influenced by shifts in sentiment towards the outlook for the Fed funds rate – remain capped on probes above the 5% level. Similarly, benchmark 10-year yields – shown in the chart below – tried to break to fresh highs last week but failed.
Further upside for yields, USD/JPY may be hard won
While yields for these tenors may eventually push higher, especially given the strong prevailing trend, recent price action suggests further upside for USD/JPY may be hard won. It also suggests that longer-term directional risks for both yields and UDSD/JPY could be skewed to the downside, not upside.
For USD/JPY traders, monitoring developments in US two and 10-year yields will complement your trading strategies, providing an additional filter when determining when to go short or long.
Jerome Powell’s Jackson Hole speech looms large
In the near-term, USD/JPY upside is likely to be capped at last week’s high around 146.50. On the downside, a support layer starting at 145.0 prevented a more meaningful reversal on Friday. Should we see a narrowing of US-Japanese yield differentials, a break of that level may lead to a decline to 144.00 and potentially 142.00. Given the sparse economic calendar, Federal Reserve chair Jerome Powell’s Jackson Hole speech on Friday looms large as a potential catalyst for a breakout in either direction.
-- Written by David Scutt
Follow David on Twitter @scutty
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NFP Preview: Can the Jobs Report Overcome the Bond Market Meltdown Too?
Traders and economists expect the NFP report to show that the US created 90K net new jobs, with average hourly earnings rising 0.3% m/m (3.1% y/y) and the U3 unemployment rate at 4.1% - see what the leading indicators are suggesting!


AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.