



USD/JPY Forecast: Yen remains under pressure after US PCE data
Near the end of the trading week, one of the most relevant moves in the FX market has been the Japanese yen’s neutrality, even after the release of the US PCE inflation data. After the data was published, USD/JPY did not register a significant move, with price action staying close to 0.05%, reinforcing a phase of short-term indecision.
Share this:
Near the end of the trading week, one of the most relevant moves in the FX market has been the Japanese yen’s neutrality, even after the release of the US PCE inflation data. After the data was published, USD/JPY did not register a significant move, with price action staying close to 0.05%, reinforcing a phase of short-term indecision.
This behavior reflects a combination of factors. On one hand, the yen has still not shown a clear recovery. On the other, the US dollar has entered a pause after several sessions of strength. Under this scenario, neutrality could continue to shape USD/JPY price action over the next few sessions.


US PCE data is released
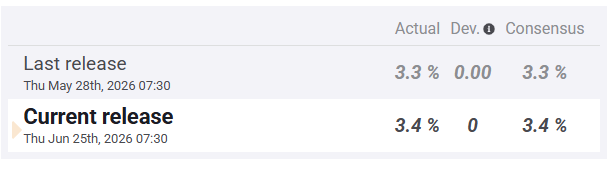
During the session, the United States published its Core PCE data, an indicator that measures changes in prices paid by consumers while excluding food and energy. The figure came in line with expectations at 3.4%, slightly above the previous 3.3% reading.
Although the release did not bring a major surprise for the market, it does confirm that inflationary pressures remain present in the US economy. This has brought some calm to expectations of higher rates, but it does not remove the underlying issue: inflation has still not shown a clear enough slowdown during 2026.
Source: FXSTREET
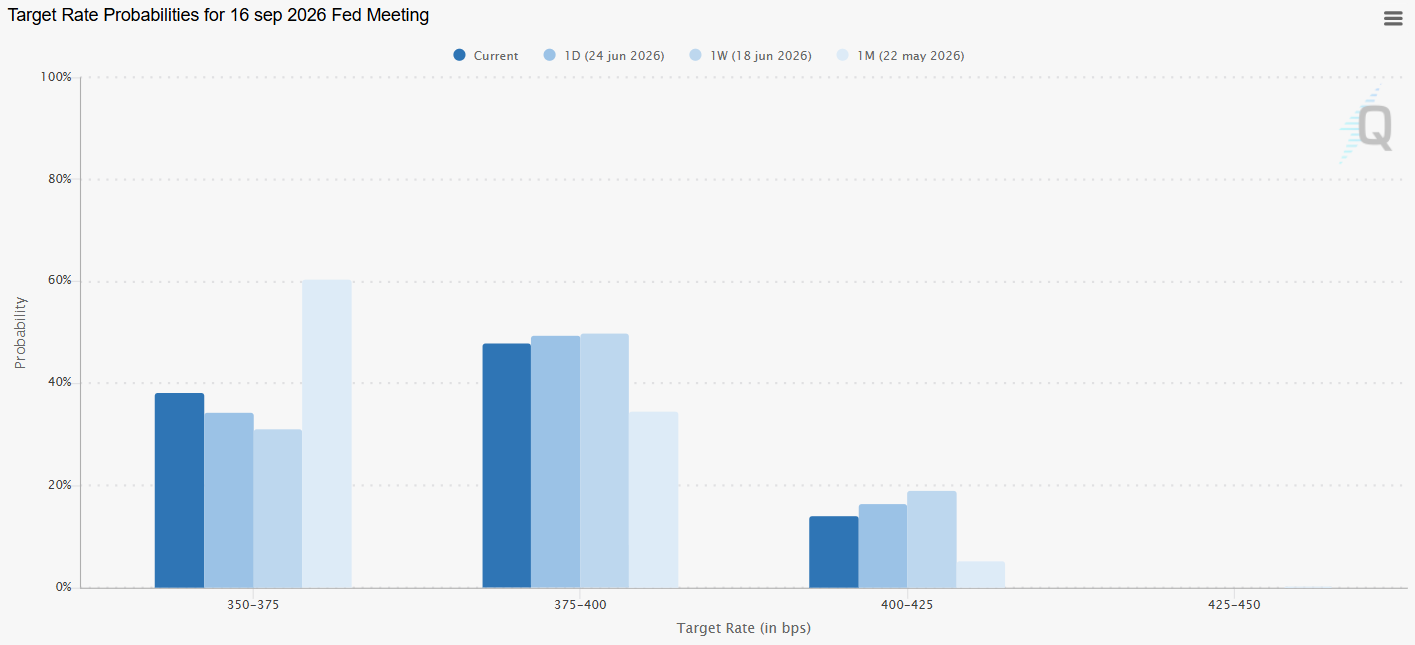
Even though the US dollar has lost some strength after the in-line data, the Federal Reserve outlook has not changed significantly. The CME Group probability table continues to show a relevant expectation of higher rates for September. After the PCE release, the probability of a rate hike moved from 49.32% to 47.80%, a moderate decline that does not fully change the scenario for the dollar.
For now, this adjustment has not been enough to meaningfully change confidence in the USD, as the market still sees a rate hike as possible over the next few months.
Source: CMEGROUP
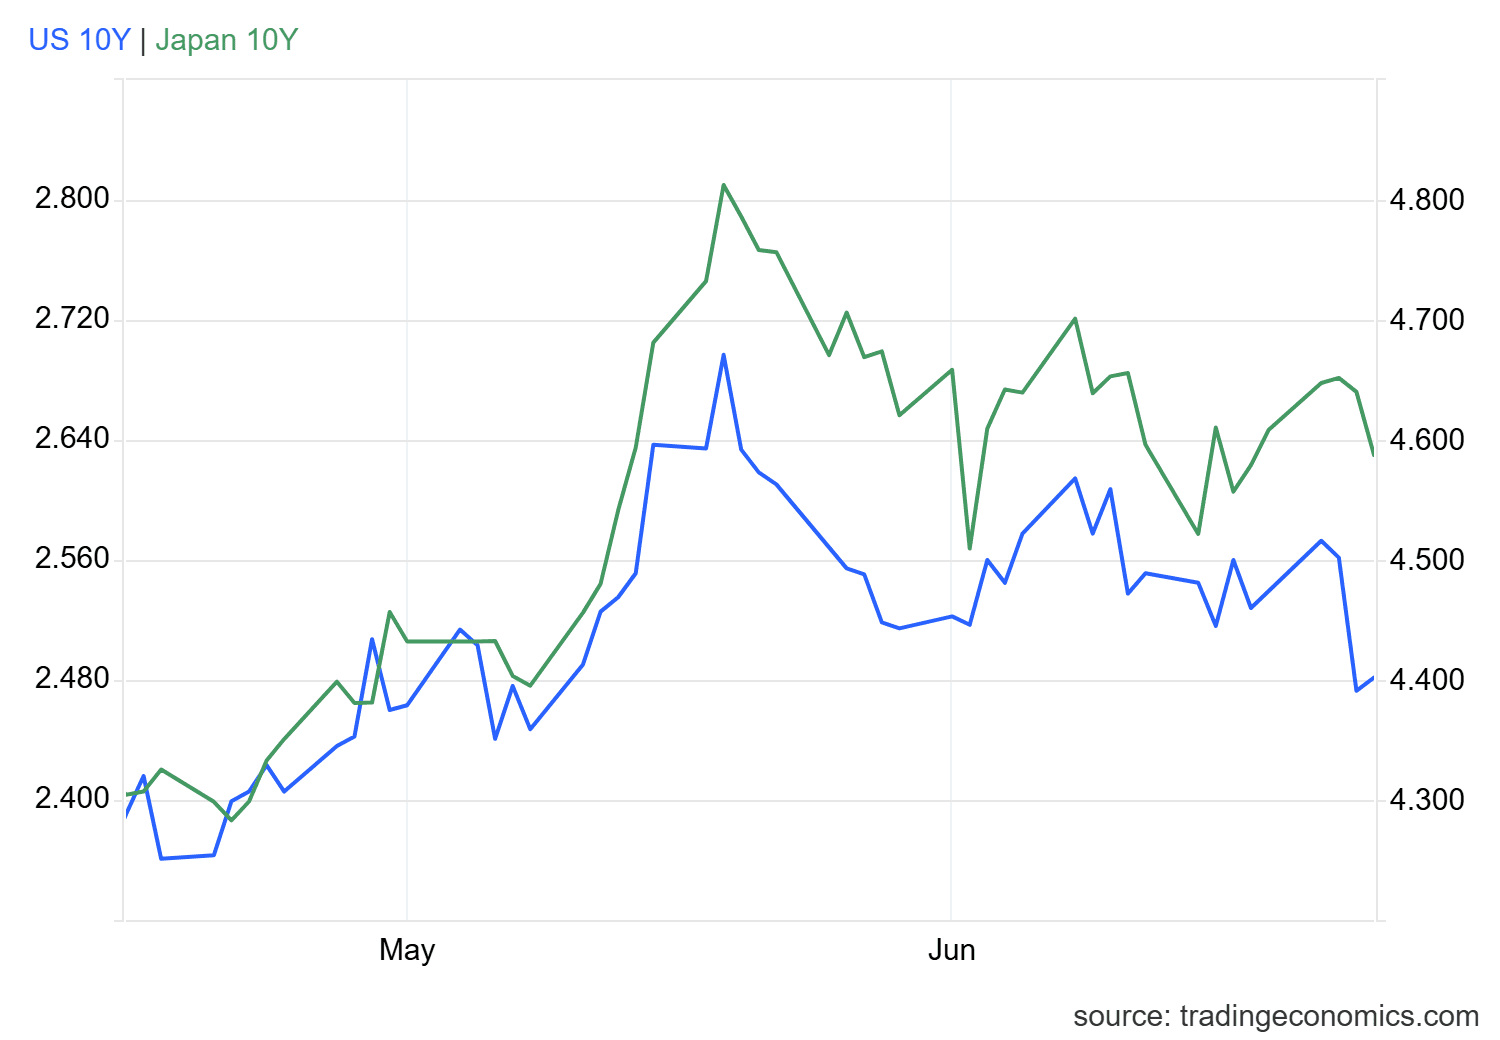
When comparing the US and Japanese bond markets, the rate differential remains an important factor. Although the US 10-year Treasury yield has pulled back toward the 4.4% area, Japanese 10-year bonds have also declined toward 2.6%. This keeps a wide gap between both markets and continues to support the appeal of dollar-denominated assets.
For this reason, recent economic data and the slight easing in US yields have not been enough to generate a meaningful shift in demand for the Japanese yen.
Source: TradingEconomics
Part of this difference also comes from the lack of clarity around the Bank of Japan. Although the institution has raised its benchmark rate to the 1.00% area, it is still unclear whether this process will continue at the late-July decision. In contrast, the Federal Reserve maintains a higher-rate outlook, which continues to support a more attractive bond market in the United States.
As long as this difference remains in place, the rate differential could continue to work against the Japanese yen and in favor of the US dollar. This could keep buying pressure in USD/JPY relevant over the next few weeks of trading.
Technical outlook for USD/JPY
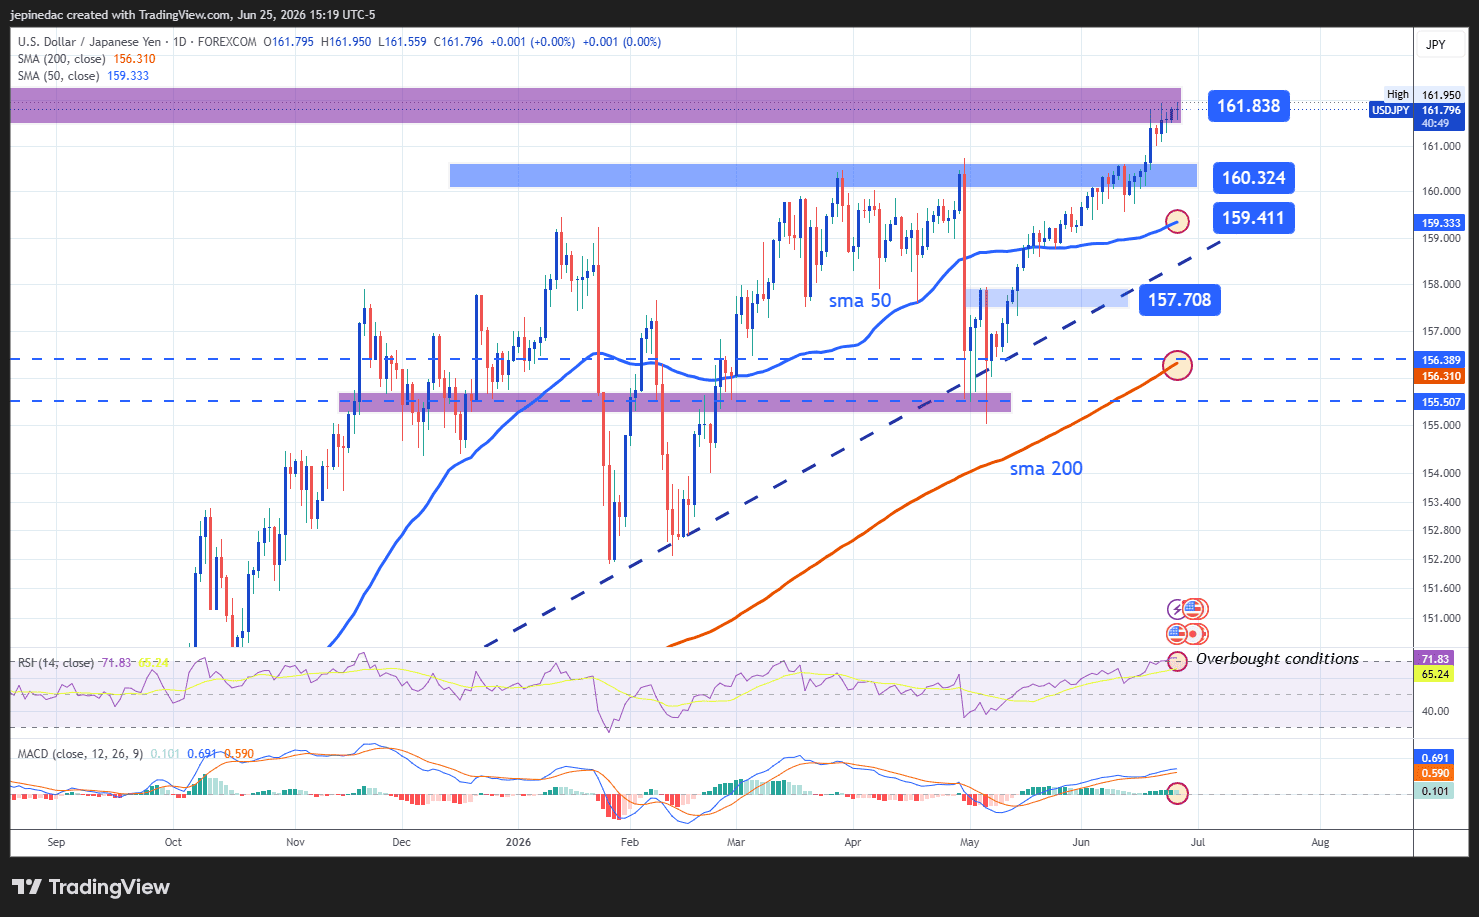
Source: StoneX, Tradingview
- The bullish trend remains dominant: For several months, the most important technical structure in USD/JPY has been a long-term bullish trendline. So far, the lack of deep bearish corrections has allowed this structure to remain the dominant pattern. If selling pressure fails to consolidate over the next few sessions, the bullish trend could continue to extend. However, the recent loss of buying momentum could also open the door to short-term bearish corrections.
- RSI: The RSI remains above the 50 neutral area, indicating that buying impulses are still relevant. However, the indicator is also above the 70 overbought zone, which suggests excess bullish strength and could open the door to short-term bearish corrections.
- MACD: The MACD histogram remains above the 0 line, showing that short-term moving averages still favor a bullish bias. As long as this dynamic continues, buying pressure could remain relevant on the USD/JPY chart.
Key levels:
- 161.838 – Key resistance: This level is linked to the 2024 highs and is currently the most important upside barrier. Sustained moves above this point could mark new relevant highs and reinforce the buying bias over the coming weeks.
- 160.324 – Nearby barrier: This recent neutrality zone also aligns with an important psychological level. It could act as a key barrier in case of short-term bearish corrections.
- 159.411 – Main support: This level coincides with the 50-period simple moving average. A strong break under this area could put the bullish trendline at risk and open the door to a more relevant selling bias over the coming weeks.
Written by Julian Pineda, CFA, CMT – Market Analyst
Follow him on: @julianpineda25
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar, GBP/USD, USD/CAD, USD/CHF, Gold Weekly Technical Outlook 11 2 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.
US Midterm Forecast: The Key Risks for Traders to Watch Through the US Elections
Prediction markets are pricing in nearly 75% odds of a Democratic sweep in this week’s US midterm elections, a development that would result in a split from the single party Republican rule of the past two years - what will it mean for markets?

GBP/USD outlook: Currency Pair of the Week | November 2, 2026
The GBP/USD heads into a crowded week of event risk, with the midterm elections, a Bank of England rate decision and Friday's non-farm payrolls report all capable of moving markets sharply. The greenback remains fundamentally well supported by a hawkish Federal Reserve, but much of that is already priced in, while the renewed sell-off in technology stocks has exposed its vulnerability.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.