


Spending surge flips RBA outlook as markets price hikes
October’s spending data shattered the Q3 gloom, lifting AUD/USD and rattling bond futures. Traders now weigh whether this momentum can hold as inflation risks resurface.
Share this:
- Household spending up 1.3%, strongest since Jan 2024
- Discretionary categories lead gains
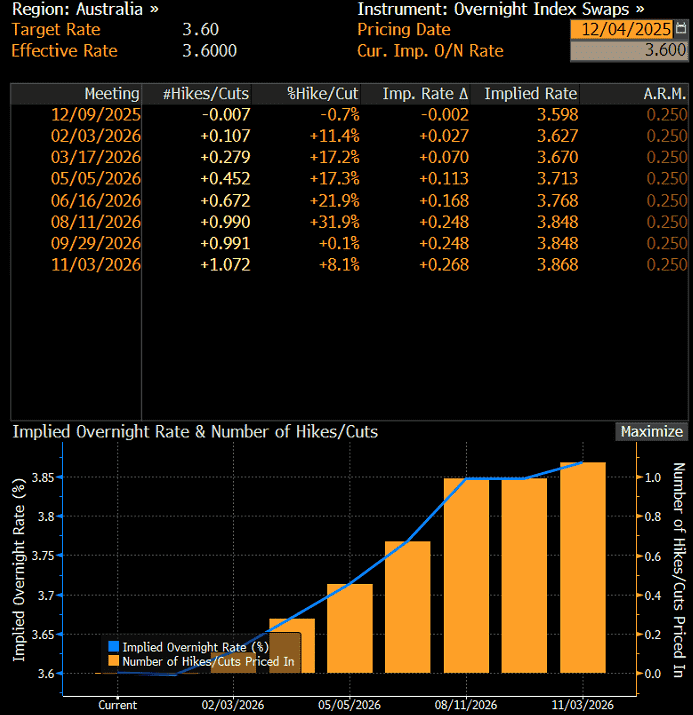
- Swaps fully price 25bp RBA hike by Nov 2026
- AUD/USD bullish bias confirmed, squeeze risk for bonds, stocks
AUD, ACGB, ASX Summary
October’s spending surge has flipped the script on Australia’s cautious Q3 narrative, fuelling RBA rate hike bets and driving AUD/USD even higher. While technicals favour Aussie bulls, bond futures look stretched, raising squeeze risk. Equities remain in limbo, with a retracement in short-dated bonds potentially the spark for a near-term rally.
Retail “Rocks” in October

Source: ABS
Australian household spending rose 1.3% in October, the strongest monthly increase since January 2024 and a clear departure from the subdued tone in Q3. The surge followed a 0.3% rise in September and left annual growth at 5.6%.
Discretionary spending drove the improvement, with goods categories rebounding after months of weakness. Clothing and footwear lifted 3.5%, furnishings and household equipment rose 3.0%, and electronics also gained. Services spending climbed, supported by major concerts and cultural festivals that boosted catering, hospitality and hotel stays. All nine categories recorded growth over the month.
The contrast with yesterday’s Q3 national accounts is stark. That report showed discretionary spend under pressure, masked by non-essential services, and a rising household savings ratio that pointed to caution among consumers. Today’s data suggests that restraint may have been temporary, with the ABS noting promotional retail events and major concerts as key drivers of the October surge. These factors imply the strength may not last, although it does coincide with a noticeable improvement in consumer sentiment and firmer consumer data overall this year.
RBA Rate Hikes Now Priced
Source: Bloomberg
With productivity growth weak and wages pressure still evident, the risk is that robust household spending may see the supply side of the economy struggle to keep pace. That could amplify the recent acceleration in inflation, raising the prospect that price pressures build further. It’s this dynamic that has seen markets shift from pricing cuts to hikes. Swaps now fully price a 25 basis point increase in the RBA cash rate to 3.85% by November next year, with a move in the first half now considered line ball by traders. The repricing has pushed the Australian dollar sharply higher while weighing on equities and government bond futures.


AUD/USD Bullish Bias Retained

Source: TradingView
AUD/USD extended its bullish move on the back of the data, pushing towards resistance at .6625. That’s the first topside level of note, followed by minor resistance at .6660 with a tougher test awaiting bulls above .6700 where the Aussie reversed hard from earlier this year. On the downside, the November high of .6580 should be on the radar. The message from the momentum indicators continues to favour bullish setups, with RSI (14) trending higher above 50 while MACD has staged a bullish crossover and is now pushing into positive territory, confirming building upside pressure.
Bond Rout Looking Fatigued

Source: TradingView
While the AUD has benefited from the recalibration in the RBA rate outlook, the price action in Australian three-year government bond futures—which are heavily influenced by monetary policy expectations—suggests those tailwinds may have run their course in the near term.
The contract is extremely oversold on RSI (14), increasing the risk of a squeeze following such a significant bearish move over the past six weeks. The inability for the price to hold most of its gains following the hot spending report hints the move may be at or near exhaustion point, suggesting we may see some form of retracement in the near term. 96.02 is the first level to watch should we see a bounce, followed by 96.08, 96.135 and 96.26.
While squeeze risk is elevated, the message from the oscillators continues to favour selling into strength unless you’re an very short-term player.
ASX Bulls and Bears Battle at 8587

Source: TradingView
The inability of rate futures to hold earlier losses may explain why ASX 200 SPI futures are managing to hang tough, with a battle royal underway between bulls and bears. 8587 is the focal point, marking where bulls continue to absorb waves of selling on moves back towards 8650. The string of dojis on the daily chart points to indecision, but given how sensitive stocks tend to be to interest rate settings, a retracement in short-dated Australian bond futures could provide the catalyst to spark a squeeze higher in equities.
With RSI (14) and MACD pointing to diminishing downside pressure, unless we see a definitive break lower towards the 200DMA, higher levels could be in play short term. If that does play out, keep an eye on the price action above 8650. If the contract can overrun the offers parked beneath the level, it would put 8750 on the radar for bulls.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.
Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.
USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.